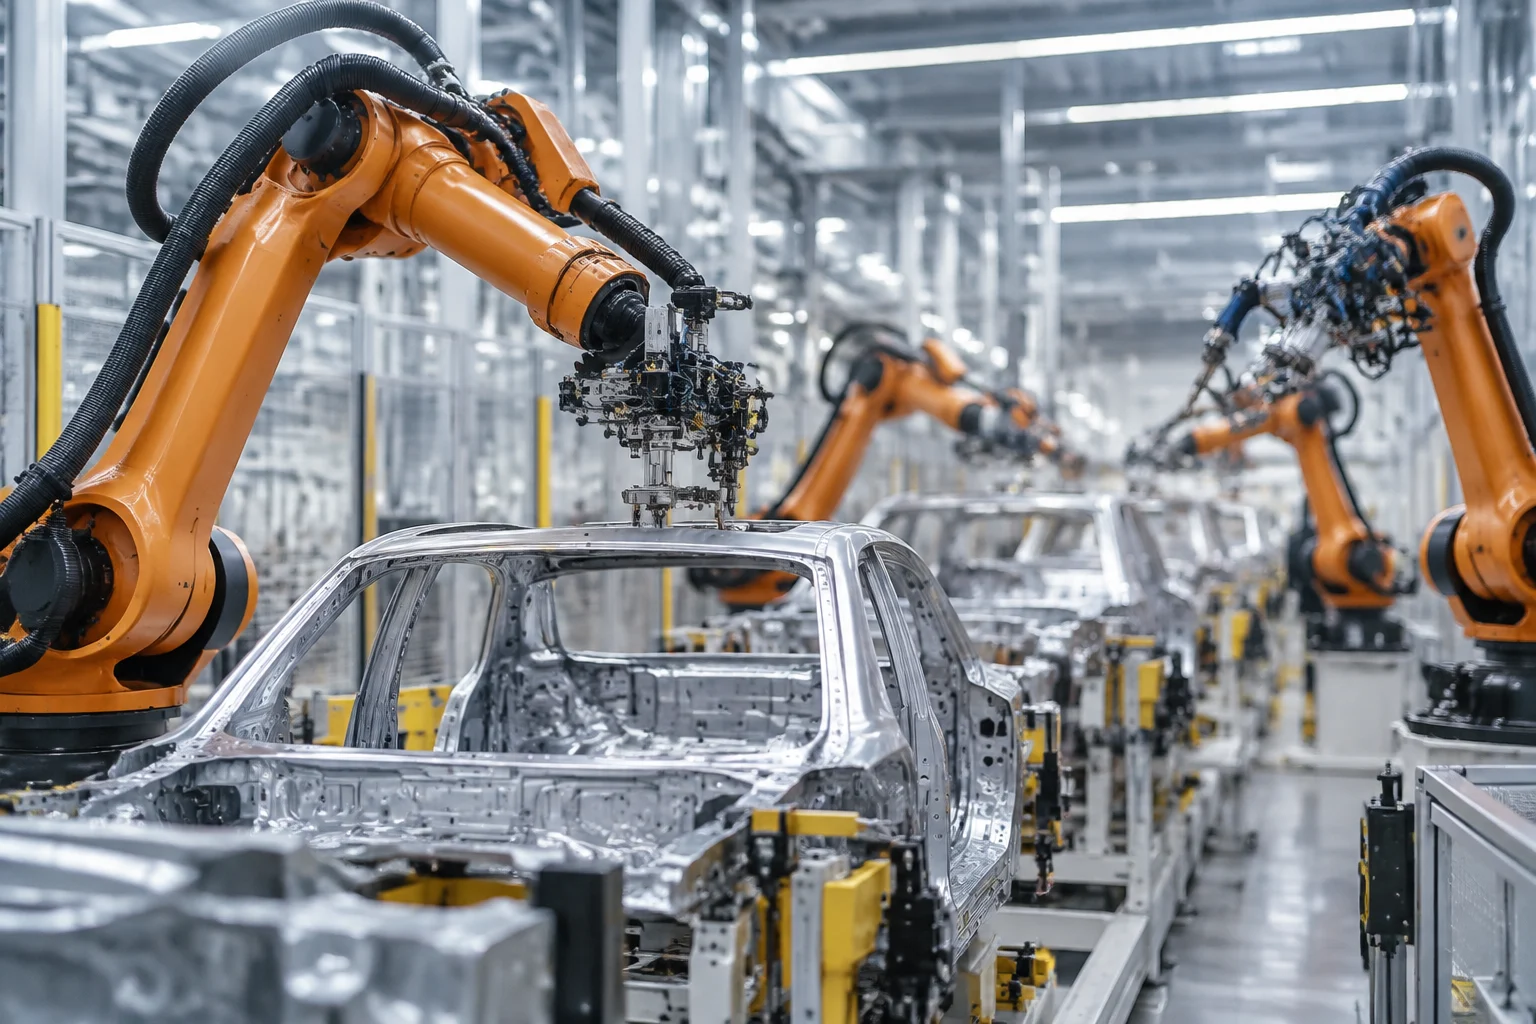
Two different figures for counting automation
Industrial robotics statistics commonly present two indicators that answer different questions: how many robots were installed in a given year, and how many are included in the operational stock. For 2025, the International Federation of Robotics (IFR) reported more than 600,000 new installations and a global operational stock of five million units. The first measures annual flow; the second is the estimated total number of operational units. They are not interchangeable measures and should not be added together as if they described the same phenomenon. The IFR reported that the stock grew by 9% compared with 2024 and that annual installations rose by 11%.
This distinction changes how the headline should be read. Annual installations indicate additions recorded during a given period; the operational stock is a separate, cumulative measure that the IFR publishes as units in use. Five million describes the estimated scale of the stock; more than 600,000 describes the rate of additions recorded for 2025. Neither figure directly measures hours of work automated or effective production capacity.
Each indicator therefore describes a different part of the change. Annual installations help track equipment entering service during a particular period; the operational stock estimates the volume that remains in use. Neither, by itself, tells us how much each robot is used or what results it produces. Keeping these measures separate avoids interpreting an annual figure as a historical total, or treating the operational stock as a measure of actual activity. (IFR)
What changed in 2025: growth was concentrated
The global figure conceals a highly uneven distribution. China installed 354,000 industrial robots in 2025, 20% more than the previous year and 59% of global installations, according to the IFR. These figures show that expansion was not evenly distributed across markets: China’s total alone accounted for a very substantial share of the worldwide figure. The global record should therefore not be read as an equivalent acceleration across all industrial economies. (IFR)
Percentages and absolute volumes offer complementary perspectives. A high growth rate does not necessarily mean that a country installed more units than another country with a lower rate, because the starting point also matters. Likewise, equipment totals do not allow direct comparisons of automation intensity between economies of different sizes. The figures describe where recorded installations were concentrated and how they changed from the previous year, but they cannot replace relative indicators or explain why those changes occurred.
The regional distribution in 2024 provides a point of comparison, although it does not replace a country-level breakdown for 2025. In 2024, Asia accounted for 74% of new installations, Europe for 16% and the Americas for 9%, according to the IFR. The comparison shows geographical concentration that year, but those percentages do not describe the tasks performed by the equipment or the share of each region’s production that depends on it. (IFR)
Putting the record in perspective
The preceding years help distinguish a one-off high from a longer-term trend. The 2025 edition of World Robotics recorded 542,000 installations in 2024, more than twice the number ten years earlier and above 500,000 for the fourth consecutive year. It also estimated an operational stock of 4.664 million robots in 2024, up 9% from the previous year. Against that backdrop, the 2025 figures—more than 600,000 installations and five million in operation—suggest that aggregate expansion continued. The comparison is useful, although figures from different editions should be understood within the series published by the IFR itself, not as an independent external audit. (IFR; IFR)
The regional dimension also matters when assessing continuity. In 2024, Asia accounted for 74% of new installations, Europe for 16% and the Americas for 9%, according to the IFR’s September 2025 publication. For 2025, the organisation identified Asia as the main driver, followed by the Americas, while Europe advanced more slowly. This comparison points to geographical concentration, but it does not describe the tasks performed by the equipment or the proportion of each region’s output that depends on it. Nor is it enough to compare absolute installations: assessing automation intensity would require relating robots to manufacturing employment, output, industries and plant size. That context is not contained in the aggregate global figure. (IFR; IFR)
A sequence covering several years adds context because it helps distinguish sustained growth from a fluctuation limited to one period. Even so, continuity in aggregate data does not mean that every country or industry follows the same path. It is also worth remembering that the 2024 and 2025 figures refer to different periods and come from IFR publications; the comparison is a reference within that series, not an independent assessment of each estimate. The annual record matters as an indicator of scale, but interpreting it depends on retaining both the time frame and the geographical level of each figure.
What installation figures cannot establish
A robot count does not prove that labour productivity or total factor productivity has increased. Demonstrating such an effect would require observing economic outcomes and comparing relevant companies or plants, while accounting for investment, process changes, demand, training, product mix and other factors that may influence results at the same time. The IFR publishes statistics on installations and operational stock, not a causal evaluation of productivity. It would therefore go beyond the published figures to claim that the record “proves” a productivity improvement. It may be consistent with improvements in certain operations, but the data do not quantify that possibility.
Nor can we infer a net employment effect or conclude that each robot replaces a person. The total does not show how many jobs are created to integrate, programme or maintain systems, which jobs change, or over what time frame. Effects may vary by industry, occupation, company and economic context; answering the question requires specific labour studies, not installation data alone. Similarly, the count does not tell us which particular tasks are automated, how many hours each unit operates, how fully it is used, or whether a plant uses it to expand capacity, address vacancies or reorganise production. An installed robot does not automatically mean a job eliminated or a fully automated factory. The figure indicates equipment adoption, not a social or economic balance sheet.
The distinction is between counting the presence of a technology and measuring its consequences. To assess productivity, for example, it would not be enough to know that robots were added: we would also need to observe what happened to output and the resources used, while accounting for simultaneous changes that could affect results. Analysing employment would require information on jobs, occupations and comparable periods. These questions call for data and methods different from those used to count installations. This does not rule out possible effects; it defines what can be supported by these figures without attributing more to them than they can show.
What to follow after the headline
To assess whether growth is translating into broader industrial change, it is useful to track annual installations and operational stock separately and check their development across several editions. Country, end-use industry and application breakdowns can then be examined where available. Comparisons should specify the level of detail provided and avoid treating countries, industries or periods with different coverage as equivalent. This methodological caution does not invalidate the aggregate installation figure published by the IFR; it defines which further comparisons the available information can support.
A stronger economic assessment would combine those series with independent indicators of manufacturing output, investment, employment, wages and productivity, taking care to compare compatible units and periods. It would also help to know how robots are actually used, rather than simply whether they are present: the installed total reveals nothing about shifts, utilisation, age or performance. The most defensible conclusion is limited: global adoption of industrial robots reached a new high in 2025 and was heavily concentrated in Asia, especially China. Additional metrics are needed to determine what that means for productivity, employment or the automation of tasks.
When combining sources, it is also important to check that categories and time periods match. An output indicator for one year cannot necessarily be linked without adjustment to installations reported for another period; nor does a total robot count provide, by itself, the denominator needed to compare plants or industries. Uneven coverage across breakdowns means analysts should state when a comparison is possible and when data at the same level of detail are missing. Installation figures can form part of a broader analysis, but they do not replace the specific measures required to answer economic or labour questions.